Beyond Auditor-General’s ₦5.5 Billion Cash Discrepancy: Adeleke’s Government Faces Wider Questions Over Debt, Payroll, Revenue and Public Funds

By Reloaded News
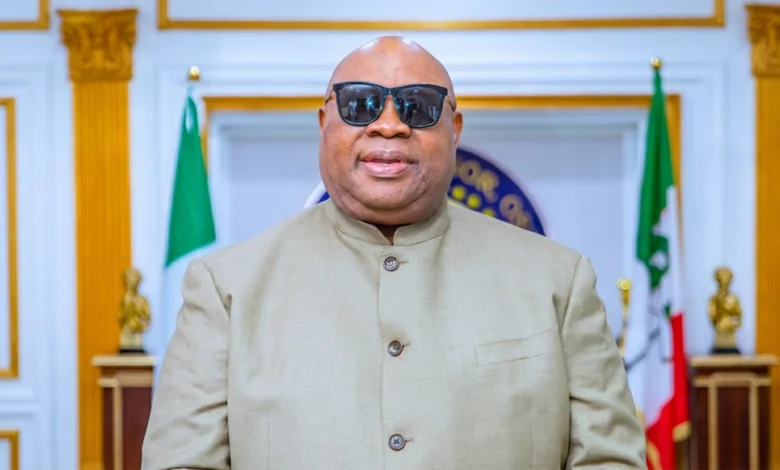
The questions raised by the Osun State Auditor-General over the government’s financial records have drawn attention to a wider set of fiscal and accountability issues confronting the administration of Governor Ademola Adeleke.
While the Auditor-General’s 2025 report highlighted a ₦5.5 billion discrepancy between reported cash balances and bank-confirmed figures, as well as ₦206.9 million associated with the defunct Heritage Bank, other developments involving the state’s debt obligations, payroll verification, government accounts and contractual commitments have continued to attract public attention.
Taken together, these developments raise broader questions about the management of public resources, the reliability of government financial reporting and the effectiveness of financial controls across the state.
Different Figures in Official Government Financial Reports
One of the issues attracting attention is a reported difference between two official documents covering Osun’s 2025 financial year.
A comparison of the state’s Fourth Quarter Budget Implementation Report and its audited financial statements identified a difference of approximately ₦29.02 billion in reported capital expenditure.
The budget implementation report recorded capital expenditure of approximately ₦133.12 billion, while the audited financial statements put the figure at approximately ₦162.14 billion.
Both documents reportedly used the same final capital budget of approximately ₦167.03 billion.
The comparison also identified a difference of approximately ₦42.02 billion in reported revenue.
These differences do not establish that money was missing or misappropriated. However, they raise questions about how the government reconciles figures across its financial publications and how members of the public can obtain a consistent account of revenue and expenditure.
Debt Obligations and the Cost of Government
Osun’s debt position provides another important dimension to the discussion.
BudgIT’s 2024 State of States report put the state’s total debt stock at approximately ₦223.07 billion as at December 2023.
The report also identified outstanding obligations relating to salaries, pensions, gratuities and contractors. Its assessment placed Osun’s debt-to-revenue ratio at approximately 143.94 per cent for the period.
There has, however, been a reduction in domestic debt. Debt Management Office figures showed that Osun’s domestic debt declined from approximately ₦148.37 billion in December 2022 to ₦79.19 billion in March 2026.
Despite that reduction, the state’s reported public debt charges for 2025 stood at approximately ₦27.44 billion.
The relevant question is therefore not simply how much the state owes, but how much it spends servicing its obligations and what remains available for infrastructure, healthcare, education and other essential services.
Disagreement Over ₦13.7 Billion Payroll Audit
In January 2026, Sally Tibbot Consulting Limited, a firm engaged in a personnel verification exercise, alleged that it had identified 15,161 workers and pensioners it classified as ghost beneficiaries.
The consultant claimed that the affected names accounted for approximately ₦1.14 billion in monthly payments, equivalent to about ₦13.72 billion annually.
The Osun Government rejected the consultant’s findings and disputed the figures.
According to the government, its own verification exercise identified 1,316 personnel who could not be confirmed. The consultant subsequently maintained its position.
The conflicting claims have raised questions about the state’s payroll verification process and the actual number of personnel whose employment or pension status requires clarification.
The allegations have not been established as proven fraud. Nevertheless, the disagreement demonstrates the importance of credible personnel records and transparent payroll management.
EFCC Investigation Into Alleged ₦11 Billion Transactions
The Economic and Financial Crimes Commission also confirmed an investigation involving approximately ₦11 billion in transactions connected with Osun’s Ecology Funds, Intervention Funds and FAAC allocations.
The commission said it had questioned government officials, including the Accountant-General, as part of its investigation.
Certain accounts were reportedly restricted during the process. However, subsequent reporting indicated that the restrictions were lifted following intervention by President Bola Tinubu.
The lifting of the restrictions does not, by itself, establish that every issue under investigation had been resolved. Equally, the existence of an investigation is not proof of financial misconduct.
The development remains relevant to the wider discussion about the management and accountability of public funds.
Gamji Arbitration Dispute and Government Bank Accounts
Another financial issue concerns the dispute between the Osun Government and Gamji Nigeria Company Limited over water infrastructure contracts in Ilesa West.
Following an arbitration award in favour of the company, the Federal High Court in Lagos ordered commercial banks to place a Post No Debit restriction on certain Osun Government accounts to preserve funds up to approximately $13.92 million and ₦157.5 million.
The Osun Government challenged the arbitration award, raising objections to the process and taking legal steps against its enforcement.
The restriction was a preservation measure in connection with the proceedings, not a final judicial determination of every issue in the dispute.
Nevertheless, the case highlights the potential financial consequences of unresolved contractual disagreements and the importance of ensuring that government projects, contractual commitments and payment obligations are properly managed.
Revenue Performance: A More Balanced Picture
Osun’s internally generated revenue also deserves examination.
BudgIT reported that the state’s IGR declined from approximately ₦29.56 billion in 2022 to ₦27.49 billion in 2023, making Osun the only South-West state to record a year-on-year decline in that assessment.
However, the state’s reported IGR subsequently increased to approximately ₦54.7 billion in 2024.
This improvement is an important part of the financial picture and should not be ignored. It also makes the question of how effectively the government converts increased revenue into public services and infrastructure more relevant.
Higher revenue must be accompanied by reliable accounting, effective expenditure controls and transparent reporting.
Public Accountability Beyond Political Arguments
The issues surrounding Osun’s finances involve different documents, institutions and legal processes. They should not be treated as evidence of a single established wrongdoing.
However, they collectively demonstrate why public financial accountability must extend beyond political statements and periodic budget announcements.
Residents and taxpayers have a legitimate interest in knowing how much money enters government accounts, how it is distributed, what obligations remain outstanding and whether public expenditure is properly documented.
The Auditor-General’s findings have brought renewed attention to the reliability of the state’s financial records. The additional questions surrounding budget figures, payroll verification, debt servicing and contractual disputes make the need for clear public explanations even more important.
For Governor Ademola Adeleke’s administration, the responsibility is to provide credible explanations for the discrepancies and controversies, demonstrate the effectiveness of its financial controls and ensure that the state’s financial records offer a consistent account of public resources.
Ultimately, the issue is not merely about competing political narratives. It is about whether the people of Osun State can rely on the government’s financial records to understand how their money is being managed.